
Dividing an Expensive Marital Home: Trusts, LLCs, and the Forced-Sale Question
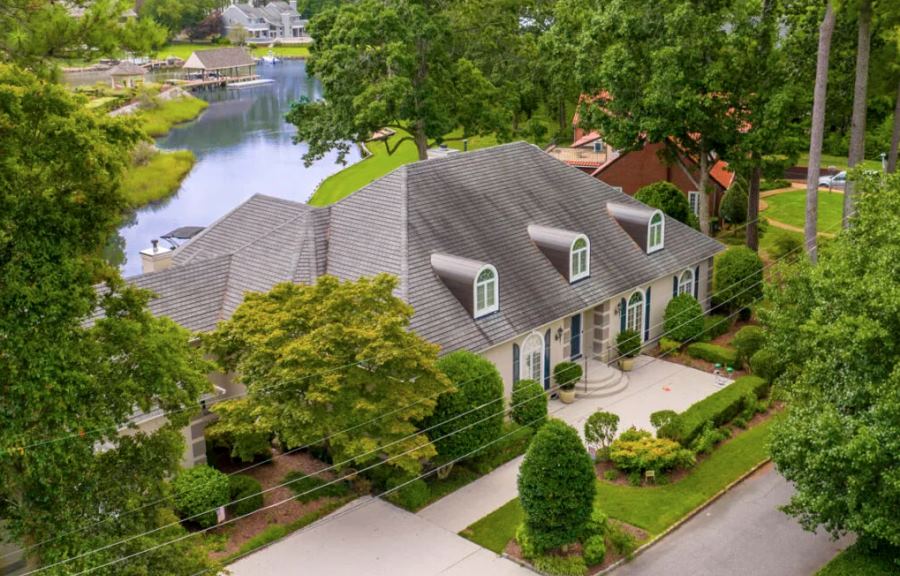
When the marital home is worth several million dollars, the usual questions about who keeps it get harder. Neither spouse may be able to carry the mortgage, the taxes and the insurance alone. The title may be in a trust or a limited liability company, which changes what a divorce court can divide. And the cost of getting it wrong, whether in a forced sale or in a poorly drafted agreement, is much larger. This page explains why an expensive home is different, what happens when title is held in a trust or an LLC, what the realistic options are, and what to gather before you meet with a lawyer.
Our family law team handles property cases for owners and for their spouses. As a San Antonio divorce lawyer practice, we begin with the deed, the loan and the trust or company papers, and our page for a high-asset divorce lawyer in San Antonio covers how larger estates are handled. The first consultation is free.
The Forced-Sale Problem Unique to Expensive Homes
When a modest home is divided, one spouse often refinances and buys out the other. That works when the loan is small and the keeping spouse’s income supports it. With a high-value property, the numbers may not work for either spouse alone. The loan can be large, the property taxes and insurance are substantial, upkeep is expensive, and the spouse who keeps the home may also be receiving fewer liquid assets because the other spouse is awarded investments or business interests to balance the division. A sale can start to look unavoidable even when neither spouse wants one.
Three points are worth understanding before you decide:
- The lender is not a party to the divorce. A decree can award the home to one spouse, but it does not by itself release the other spouse from the loan. Releasing a spouse from the note usually takes a refinance, an assumption the lender agrees to, or another arrangement with the lender.
- Federal law limits a lender’s ability to demand payment of the whole loan just because the home was transferred in a divorce. For residential property of one to four units, a lender generally may not enforce a due-on-sale clause because of a transfer to the borrower’s spouse or a transfer under a divorce decree or a property settlement agreement (12 U.S.C. 1701j-3(d)). That protects the loan from being called. It does not require the lender to release the departing spouse.
- Texas law allows a lien that secures the equity one spouse owes the other. The Property Code lists, among the encumbrances that may be fixed on a homestead, an owelty of partition imposed by a court order or a written agreement, including a debt of one spouse in favor of the other resulting from a division or an award of a family homestead in a divorce (Section 41.001(b)). Our guide to the owelty lien on a house explains how that works in a buyout, and our page on a mortgage in one spouse’s name covers the loan.
Our page on real estate and marital home division covers the general rules, and our guide to what happens to the house in a Texas divorce answers the common questions. This page concentrates on what changes when the home is expensive or when title is not in a spouse’s name.
First Question: Whose Home Is It?
The answer starts with character. Property a spouse owned before the marriage, or received by gift, devise or descent, is that spouse’s separate property (Family Code Section 3.001). Other property acquired during the marriage is community property (Section 3.002). Property that either spouse holds when the marriage ends is presumed to be community property, and the spouse who claims it is separate must prove that by clear and convincing evidence (Section 3.003). A court divides community property in a manner it considers just and right (Section 7.001), and it does not award one spouse’s separate property to the other.
Separate property does not always end the discussion. A home bought before the marriage may have been paid down, improved or refinanced with community money. The community estate can have a claim for reimbursement in that situation, and the amount is determined under the equitable principles in Section 3.402. Our page on reimbursement claims explains how those claims work. In a high-value case, a reimbursement claim can be worth a great deal, and it is easy to overlook when the home is in one spouse’s name.
When the Home Is Held in a Trust
A home held in a trust is not analyzed like a home titled in a spouse’s name. The trustee holds legal title, and the first questions are who created the trust, who funded it, what the trust document says and what rights each spouse has under it. There are two common situations.
- The spouses created and funded the trust themselves, often a revocable living trust, with property they acquired during the marriage. The trust is usually a way of holding title, and the character of the home generally depends on how and when it was acquired, not on the trust label. Moving a home into a trust does not by itself change whether it is community property, so the trust agreement should be read.
- One spouse is a beneficiary of a trust that someone else created, such as a parent or grandparent, and the trust owns the home. The home belongs to the trust. What the spouse owns is a beneficial interest, and what that interest includes depends on the trust’s terms.
What Actually Gets Characterized
For distributions a spouse receives from a trust, Texas courts ask whether the beneficiary has a present possessory right to part of the trust’s principal, which is the corpus. In Sharma v. Routh, a Houston court of appeals held in 2009 that income distributions are community property only if the recipient has a present possessory right to part of the corpus, and that a beneficiary who did not have that right acquired the distributions by gift or devise, so they were separate property. The court also held that serving as trustee was not a controlling factor. A San Antonio court of appeals reached the same result in Benavides v. Mathis (2014), where the trust was irrevocable and the beneficiary had no present possessory right to any part of the corpus, so the distributions were separate property.
Those decisions concern distributions, not a house, and they do not tell you whether a particular trust-held home is part of the marital estate. They do show the question a court asks: how much control does the spouse have over the trust property? A spouse who can compel distributions of principal or revoke the trust is in a different position from a spouse who can receive only what a trustee chooses to distribute.
Why This Gets Contentious
Trust cases are litigated because the outcome turns on documents, not on a rule: the trust instrument and its amendments, the transfer deeds, the trustee’s records and the history of who paid for the home and its upkeep. A family trust created by one spouse’s parents often gives the other spouse no direct interest, but it can give the beneficiary spouse the right to live in the home without paying rent, and that right can matter to the settlement even if the home cannot be divided. The Property Code also treats a home held by a “qualifying trust” as the homestead of a settlor or beneficiary who occupies it, if the trust gives that person the right to revoke, a general power of appointment or rent-free occupancy (Section 41.0021). Whether a trust meets that definition affects the homestead rules that apply to the home.
When the Home Is Held in an LLC
Holding a home in a limited liability company is common for liability protection and estate planning. It raises a separate legal question, because the company, not a spouse, holds title.
The Entity Theory of Property
Under the Business Organizations Code, a membership interest in a limited liability company is personal property, and a member has no interest in specific property of the company (Section 101.106). A Texas court of appeals applied that rule in a divorce in DiBassie v. DiBassie (Beaumont 2022), holding that the property subject to division was the interest in the company and not the company’s specific assets. The statute also says a membership interest may be community property under applicable law.
The result is that a court generally divides the spouses’ membership interests, not the house. If the LLC was formed with community funds or the interests were acquired during the marriage, the interests are likely to be community property, and each spouse’s claim is to a share of the company. The value of an interest in an LLC that holds a home may differ from the value of the home, and the company agreement controls how the property can be used, sold or distributed. Our guide to business valuation methods explains how those differences are priced.
Ownership through a company also affects the home in practical ways. The homestead protections in the Property Code, including the owelty lien rule, are written for a homestead, and the section on trusts extends them to qualifying trusts, and it says nothing about companies. Whether a home owned by a company is a homestead is a question to ask before the settlement is drafted, because it affects the lien that secures a buyout.
The Anti-Abuse Safeguard
A spouse cannot safely shield a home by moving it into a trust or a company shortly before or during a divorce. A temporary restraining order in a divorce can prohibit a spouse from selling, transferring, mortgaging or encumbering property without permission (Family Code Section 6.501). Fraud is presumed when one spouse disposes of the other spouse’s interest in community property without that spouse’s knowledge or consent, and a court that finds fraud on the community can award the injured spouse a disproportionate share of the estate to make up for it. A transfer made to defeat the other spouse’s claim can also be challenged under the law of fraudulent transfers. If you think your spouse is moving property, or you are considering a transfer yourself, talk to a lawyer before anything is signed. Our guide to hidden assets in divorce explains how transfers are traced.
Practical Options When Standard Approaches Don’t Fit
An expensive home calls for choices that a standard division does not offer. The realistic options include:
- A buyout financed with a new loan, with or without an owelty lien. The spouse who keeps the home refinances, qualifies on income and assets, and pays the other spouse the agreed equity. A jumbo loan has stricter underwriting, so we confirm early that the spouse can obtain one.
- A trade of other assets. One spouse keeps the home and the other receives investments, retirement accounts or business interests of comparable after-tax value. The comparison has to account for taxes, since a dollar in a retirement account is not worth a dollar in cash.
- A deferred sale. The spouses agree that one of them, often with the children, stays in the home for a set period or until a stated event, and the home is then sold and the proceeds divided. The agreement should say who pays the mortgage, taxes, insurance and repairs, who decides the listing price and the broker, what happens if the home does not sell and how disputes are resolved. Vague terms here are the usual cause of later litigation.
- Continued co-ownership for a limited time. This is less common, and it needs a written agreement about use, costs and a path to a sale.
- A sale ordered by the court. When the spouses cannot agree and neither can keep the home, the court can order it sold and the proceeds divided as part of a just and right division. It is usually the last resort, because it gives up control over timing and price.
A divorce mediation lawyer in San Antonio can help the spouses negotiate these terms, which a court is unlikely to design for them. A negotiated deferred sale, for example, can be drafted to fit the family’s schedule in a way a judge’s order usually cannot.
Taxes on the Home
A transfer of property between spouses incident to a divorce is generally not taxed when it is made, and the spouse who receives the property takes the transferor’s tax basis (26 U.S.C. 1041). A court can also consider whether an asset will be taxed and when (Family Code Section 7.008). On a sale, a homeowner who owned and used the home as a principal residence for two of the last five years may exclude up to $250,000 of gain, or up to $500,000 on a joint return when the conditions are met (26 U.S.C. 121). On a home that has appreciated for many years, the gain can exceed those limits, so the tax cost of a sale belongs in the comparison of options. Your CPA should confirm how the rules apply to your property.
Carrying the Home While the Case Is Pending
Someone has to pay the mortgage, taxes and insurance while the case is pending. After notice and a hearing, a court can make temporary orders that include a sworn inventory, exclusive occupancy of the residence, limits on spending and support (Family Code Section 6.502). The statute does not expressly say the court orders a particular mortgage paid, so the practical approach is to raise it early and, if possible, agree on who pays what in a written temporary agreement. A spouse should not stop paying, move out or change the locks without advice. A missed payment can harm both spouses’ credit and leave the home exposed, and the order of events can affect what the court later does.
More About High-Net-Worth Divorce in San Antonio
These guides cover related questions in more depth. Each one is written for Texas and Bexar County.
- Stock options and executive compensation: dividing equity pay earned during the marriage.
- Oil, gas and mineral rights: how royalties, bonuses and delay rentals are characterized.
- Keeping a divorce private: what can be sealed and what stays public.
- High-income child support: how support works when income is above the guideline cap.
- Spousal maintenance in high-net-worth divorce: when support after divorce is available and how long it lasts.
- Whether assets are split 50-50: how a court divides what is community property.
- San Antonio property division lawyer: how the property division process works from the inventory to the decree.
- The Texas Family Code: how the code is organized and where these rules sit.
How We Approach an Expensive Home
Barton & Associates has tried Texas cases since 2001, and the family law team includes Duane Graeff, our managing attorney with more than 26 years in Texas state and federal courts, and trial attorney Désirée Flye. We represent the spouse who wants to keep the home and the spouse who wants it sold, and we tell you which side we are on from the first meeting.
We start with the deed, the loan and the trust or company documents, because they show who owns the home and what a court can divide. Then we compare the realistic options with the numbers, including the loan terms, the taxes and what each spouse can carry.
Get a Real Answer for Your Specific Situation
An accurate answer needs the documents in front of us. Our San Antonio office is at 115 Camaron Street, San Antonio, Texas 78205. You can get directions to our office before your visit. For the first meeting, bring what you can of the following, and call even if you cannot find everything.
- The deed, the closing statement and any title policy
- The mortgage note, the latest statement and any home equity or other loan documents
- The trust agreement and amendments, and the deed that transferred the home to the trustee, if a trust holds title
- The articles, company agreement and membership records, if a company holds title
- A recent appraisal, tax statement and homeowner’s insurance policy
- Records of improvements, major repairs and payments on the loan from separate funds
- Records of the home’s cost basis, such as the purchase price and improvements, for the tax discussion
- Any prenuptial or postnuptial agreement
- Papers you have been served with, if a case has already been filed
Frequently Asked Questions
If Our Home Is in an LLC, Does That Mean My Spouse Can’t Get Any Share of It?
No. A member of an LLC has no interest in the company’s specific property, so a court generally divides the membership interests, not the house (Business Organizations Code Section 101.106). A membership interest can be community property, and a spouse can claim a share of it if it was acquired during the marriage or funded with community money. The value of that interest, and how the company agreement limits its sale, will drive the result.
Can My Spouse Move Our House Into a Trust Right Now to Keep It Away From Me in the Divorce?
A spouse can try, but it is risky and it can backfire. A temporary restraining order can prohibit transfers of property without permission (Family Code Section 6.501), fraud on the community is presumed when one spouse disposes of the other’s interest without consent, and a court can adjust the division to make up for it. If you believe a transfer is being planned or has happened, call a lawyer promptly and gather the deed and any recorded documents.
Our Home Is Held in a Family Trust My In-Laws Created. Does That Change Anything?
Often yes. When a third party’s trust owns the home, the spouse is a beneficiary and the divorce court divides what the spouses own, not the trust’s property. Whether a distribution is separate or community property can turn on whether the beneficiary has a present possessory right to part of the trust’s principal (Sharma v. Routh; Benavides v. Mathis). The right to live in the home may also be set out in the trust. The document controls, so it must be reviewed.
What Happens If Neither of Us Can Afford to Keep the House on Our Own?
The common outcomes are a sale, a deferred sale in which one spouse stays for a set period, a trade in which one spouse takes the home and the other takes other assets, or a court-ordered sale if nothing else works. The right choice depends on the loan, the taxes and the other assets in the estate, and the agreement should say who pays the carrying costs in the meantime.
Should I Try to Buy Out My Spouse’s Interest in Our Expensive Home, or Just Agree to Sell It?
Compare the numbers before deciding. A buyout requires you to qualify for a loan large enough to refinance the existing debt and pay your spouse the equity, and a lien can secure the amount you owe (Property Code Section 41.001(b)). A sale gives up the home but may free both spouses and avoid carrying costs. The tax cost of a sale and what other assets can offset a buyout belong in the comparison.
Can the Court Force the Sale of Our Home?
The court divides the estate in a manner that is just and right (Family Code Section 7.001), and when the spouses cannot agree and neither can keep the home, an order that it be sold and the proceeds divided is one way to do that. It is usually a last resort. Spouses who negotiate keep more control over the timing, the price and who stays in the home.
Does Divorce Take a Spouse Off the Mortgage?
Not by itself. The lender is not a party to the divorce, so a decree that awards the home to one spouse does not release the other from the loan. Federal law limits the lender’s right to call the loan due because of a transfer to a spouse or under a divorce decree (12 U.S.C. 1701j-3(d)), but release usually requires a refinance, an assumption the lender approves or another arrangement.
Who Pays the Mortgage While the Case Is Pending?
That depends on any temporary orders and any agreement between the spouses. The court can make temporary orders after notice and a hearing, including exclusive occupancy of the residence, limits on spending and support (Family Code Section 6.502). Do not stop paying or move out without advice, because a missed payment can affect both spouses.
Will We Owe Tax If We Sell?
Possibly. A homeowner who has owned and used the home as a principal residence for two of the last five years may exclude up to $250,000 of gain, or up to $500,000 on a joint return when the conditions are met (26 U.S.C. 121). A home that has appreciated beyond those limits can produce taxable gain. Talk to your CPA early, because the answer can change how the settlement is structured.
What If the Home Is My Separate Property?
A home you owned before the marriage, or received by gift or inheritance, is your separate property, and you must prove that by clear and convincing evidence (Family Code Sections 3.001 and 3.003). The community can still have a reimbursement claim if community money paid down the loan or improved the home (Section 3.402). Keep the deed, the closing statement and records of every payment and improvement.
Does Homestead Protection Affect a Divorce?
Homestead status protects the home from most creditors, but it does not prevent the court from dividing it in a divorce. The Property Code specifically allows a lien for the debt one spouse owes the other when a family homestead is divided or awarded in a divorce (Section 41.001(b)). If a trust or an LLC holds title, ask whether the homestead rules apply.
Talk to a San Antonio Attorney About Your High-Value Home
How a deed, a trust and a loan fit together can decide whether you keep the home, sell it or share it, and the decisions made in the first weeks are hard to undo. Speak with a divorce attorney in San Antonio at Barton & Associates about your property, your documents and your goals before you transfer, refinance or sign anything.
Call our San Antonio office at 210-500-0000 or complete the online Free Consultation form to schedule a confidential meeting with a family law attorney in San Antonio. The office is at 115 Camaron Street, San Antonio, Texas 78205.
Schedule a Free Consultation
Barton & Associates, Attorneys at Law
115 Camaron St, San Antonio, TX 78205
Office: 210-500-0000
Division: Family Law San Antonio
Practice Area: Divorce & Separation
Focus Area: High-Net-Worth Divorce